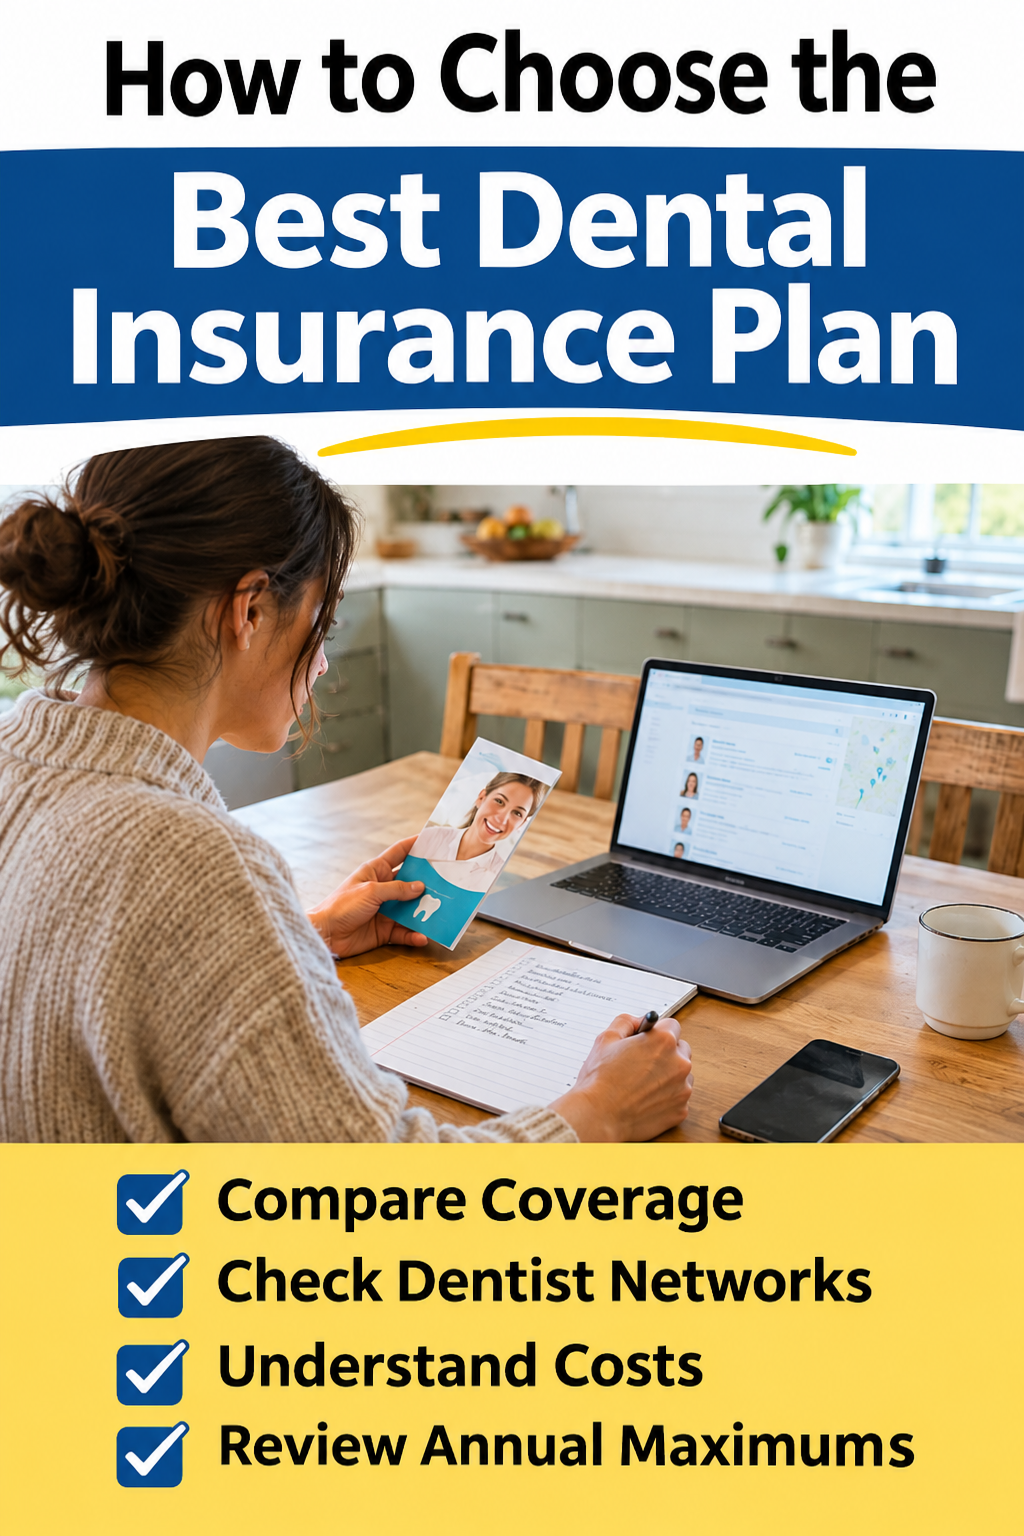
Dental coverage can make routine care and larger procedures easier to budget for, but the monthly premium tells only part of the story. Before enrolling, compare the dentist network, deductible, coverage percentages, and annual plan limit.
For people shopping outside an employer benefits package, personal dental insurance coverage from Delta Dental offers a useful real-world example of how individual and family plans can differ. Delta Dental provides dental plans and network access information for consumers, with individual PPO options listed in service areas including California, Florida, New York, and Texas. The plan information also illustrates why the state must review availability and benefits.
Why Plan Details Matter More Than The Monthly Premium
A low premium can be valuable when you expect only exams and cleanings. It may be less useful if you need fillings, crowns, root canals, dentures, or orthodontic treatment and the plan has a limited coverage, or a low annual maximum. Dental insurance also commonly has different benefit limits than major medical coverage, so it is important to review the policy rather than assume it works the same way.
People considering Marketplace options should also carefully compare Marketplace dental plans, since stand-alone plans can have separate premiums, deductibles, and covered-service rules for adult services.
The Main Types Of Dental Plans
PPO Plans
Preferred Provider Organization, or PPO, plans have a network of participating dentists. You can often see an out-of-network dentist, but your share of the cost may be higher because the dentist may not accept the plan’s negotiated fee. Before scheduling treatment, confirm that the office participates in the exact network attached to your plan.
DHMO-Type Plans
DHMO-type plans generally require members to use participating dentists and, in many cases, select a primary dentist. Instead of paying a percentage of a bill, members may pay listed copayments for covered procedures. This can make costs more predictable, although the available provider network may be smaller or more restrictive.
Dental Discount Plans
Dental discount plans are not traditional insurance. Members pay a membership fee and receive reduced fees from participating dental offices. They may be worth comparing when insurance exclusions or annual maximums do not fit your expected needs. Ask the office for its discounted fee schedule before joining.
How Networks Affect Out-Of-Pocket Costs
A dentist saying they “accept” an insurer does not necessarily mean they participate in every network offered by that insurer. Network names can be similar, while negotiated fees and coverage rules differ. A quick verification process can help avoid surprises:
- Search for the dentist or office in the plan’s provider directory.
- Confirm participation in the exact network named in the policy.
- Ask whether the office is accepting new patients.
- Request a written treatment estimate for major work.
When Coverage Starts For Different Services
Some plans do not cover every service from the first day of enrollment. Preventive care may be available right away, while basic services such as fillings and major services such as crowns may become eligible only after you have been enrolled for a set length of time. The plan sets the exact rules, and they may vary by location.
- Which services are not covered right away?
- How long must I be enrolled before those services are covered?
- Does prior qualifying coverage change when benefits start?
- Are emergency services handled differently?
- Will the plan cover treatment that started before enrollment?
Annual Maximums And Why They Matter
An annual maximum is the most a dental plan will pay toward covered services during its benefit period. After that limit is reached, you generally pay the remaining eligible costs yourself. A crown, root canal, or several fillings can use a substantial portion of a plan’s available benefit.
Check whether the maximum is $1,000, $1,500, $2,000, or another amount, and whether the plan year follows the calendar year or your policy anniversary. Also, confirm how preventive care is treated, because some plans handle those services differently from basic and major care.
Coinsurance, Copayments, And Deductibles
Coinsurance is a percentage split between you and the plan. For example, if a covered filling is subject to 80 percent plan coverage after the deductible, you may pay the remaining 20 percent plus any noncovered charges.
Copayments are set amounts for specific covered procedures. They are common in plans designed around a participating dentist network and can make expected procedure costs easier to estimate.
Deductibles are amounts you may need to pay before the plan begins sharing costs for certain services. Preventive care can have separate rules, so do not assume a deductible applies equally to every visit.
How Preventive Care Fits Into A Plan
Exams, cleanings, and X-rays are common preventive services. Coverage may still include frequency limits, age rules, or requirements about the type of X-ray. Routine visits can help a dentist identify problems early, but a covered preventive visit does not automatically mean every service provided during that appointment is free.
Questions To Ask Before Choosing A Plan
- Is my preferred dentist in this plan’s exact network?
- What is covered in the first year?
- Are fillings, crowns, root canals, implants, dentures, or braces excluded or delayed?
- What are the deductible, copayments, coinsurance, and annual maximum?
- Are referrals required for specialists?
- Can I add a spouse or dependent later?
How To Compare Two Plans Side By Side
Create a simple list for each option that includes the monthly premium, annual deductible, preventive benefits, basic-service coverage, major-service coverage, orthodontic benefits, annual maximum, network access, and out-of-network rules. Then estimate your likely dental needs for the next 12 months.
If you expect only routine care, a lower premium and strong preventive benefits may be the priority. If you already know that major treatment is likely, focus on network discounts, coverage for major services, and the annual maximum.
Common Mistakes To Avoid
- Choosing a plan before checking the dentist network.
- Assuming every procedure is covered.
- Confusing an annual maximum with an out-of-pocket maximum.
- Overlooking when coverage for major services begins.
- Relying only on a verbal estimate instead of reviewing plan documents.
Final Takeaway
The right dental plan is not always the one with the lowest premium. A stronger choice balances the premium with provider access, service coverage, cost sharing, and the annual maximum. Spending 10 minutes reviewing those details before enrollment can make future dental bills far easier to understand.